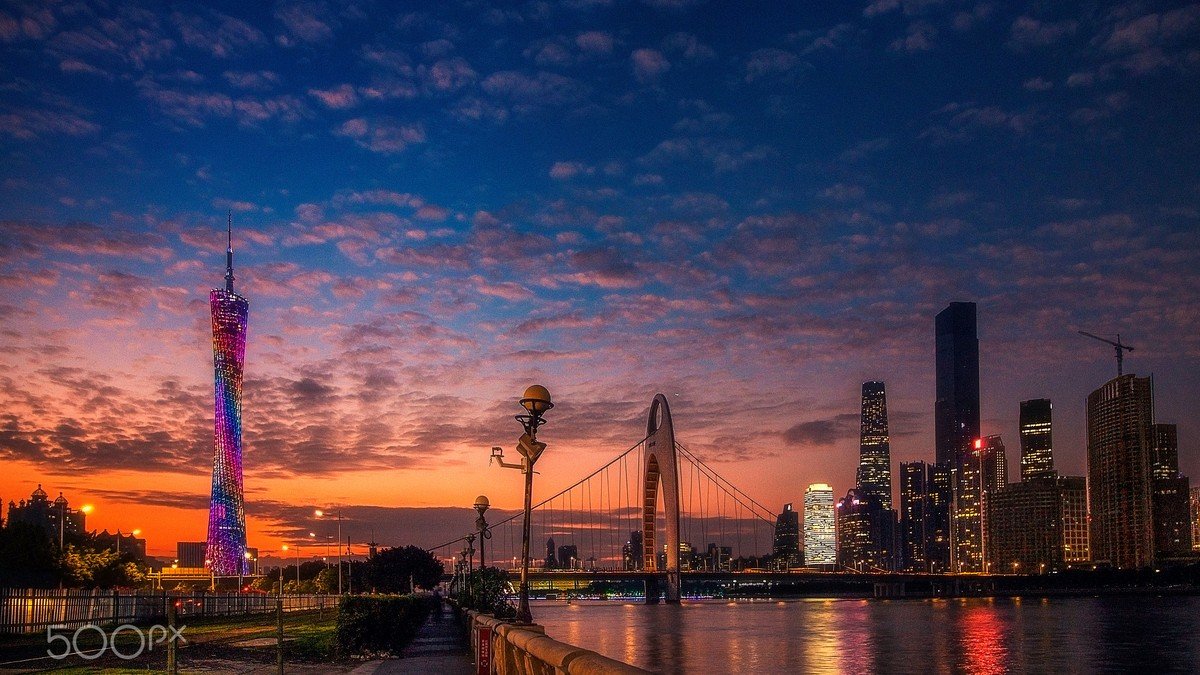
Three of China's four Tier-1 megacities—Shanghai, Guangzhou, and Shenzhen—have unveiled sweeping relaxations of residential homebuying restrictions, executing the most aggressive coordinated municipal housing intervention since China's central leadership pledged earlier in the week to halt the prolonged real estate downturn and stabilize property prices. The municipal directives lower mortgage entry barriers, shorten residency eligibility thresholds, and reduce transaction taxes across the nation's wealthiest urban markets.
In the boldest move among the top-tier metropolises, the General Office of the Guangzhou Municipal People's Government announced the complete abolition of all remaining home-purchase restrictions across every district of the southern commercial hub, effective Monday. Under the new policy, neither households with local household registration (hukou) nor non-resident buyers will face reviews of homebuying qualifications or caps on the number of residential units they may purchase.
Shanghai and Shenzhen Cut Down Payments and Residency Thresholds
Shanghai's Municipal Commission of Housing and Urban-Rural Development, acting jointly with local financial and tax regulators, issued a seven-point policy package known as the 'Hu Seven Measures.' Effective October 1, Shanghai reduced the minimum down-payment ratio for first-time commercial mortgages to 15 percent and lowered the second-home down-payment requirement from 35 percent to 25 percent—or 20 percent in designated suburban growth zones such as Lingang and Jiading. Crucially, the period of continuous income tax or social-security payments required for non-hukou residents to purchase a home in Shanghai's core districts was cut from three years to just one year.
Hours later, neighboring tech hub Shenzhen followed with parallel measures, slashing minimum down payments to 15 percent for first homes and 20 percent for second homes. Shenzhen completely lifted social-security verification requirements for non-local buyers purchasing homes in outer districts including Bao'an, Longgang, and Longhua, while reducing the requirement in central districts such as Futian and Nanshan from three years to one year.
“Coordinated easing across Tier-1 metropolitan markets is designed to unlock pent-up upgrading demand, stabilize housing prices, and restore household balance-sheet confidence.”
Tax Relief and Central Bank Monetary Support
To accelerate turnover in the secondary housing market and allow existing homeowners to trade up to larger apartments, both Shanghai and Shenzhen shortened the minimum holding period for value-added tax (VAT) exemptions on residential resales from five years to two years. Shanghai also abolished its distinction between 'ordinary' and 'non-ordinary' housing standards, a classification that had previously subjected larger family apartments to higher deed and value-added taxes.
The municipal rollouts directly reinforce the People's Bank of China's (PBOC) broader stimulus package, which includes an average 50-basis-point reduction in interest rates on existing mortgages nationwide—projected to save 50 million households approximately 150 billion yuan ($21.4 billion) annually. Real estate developers and brokerage networks across the Yangtze River Delta and Greater Bay Area reported an immediate surge in weekend showroom inquiries following the announcements.
Comments (0)
Log in to join the discussion.