

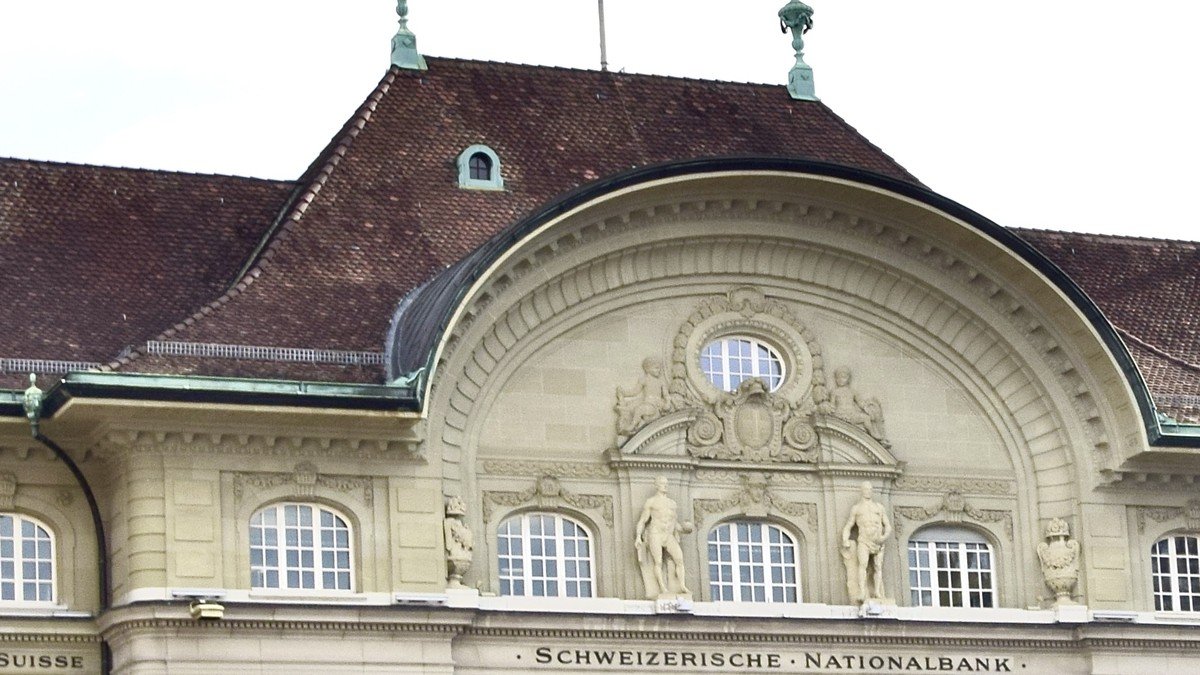
The Swiss National Bank (SNB) convenes its quarterly monetary policy assessment on Thursday, with financial markets and corporate leaders across Switzerland bracing for a third consecutive interest rate reduction. The central bank faces mounting urgency to rein in the unrelenting appreciation of the Swiss franc, which has reached multi-month highs against both the euro and the US dollar.
With headline Swiss consumer price inflation cooling to 1.1% in August—firmly anchored inside the central bank's target band of 0% to 2%—economists anticipate a 25 basis point reduction in the SNB policy rate from 1.25% to 1.00%, with several prominent investment banks pricing in the possibility of an aggressive 50 basis point cut.
Currency Appreciation Squeezes Swiss Manufacturing
The relentless strength of the franc, driven by safe-haven capital inflows amid European political volatility and Middle Eastern turmoil, has triggered intense distress across Switzerland's export-oriented manufacturing, machinery, and luxury watchmaking industries.
Industry lobbies such as Swissmem, which represents over 1,300 engineering and tech companies, reported that one-third of member firms are operating at a financial loss due to unfavorable currency conversions, urging the central bank to intervene directly in foreign exchange markets to weaken the currency.
“The strong franc creates severe headwinds for our exporters. Price stability remains our mandate, and we stand fully prepared to be active in the foreign exchange market as necessary.”
Thomas Jordan's Final Policy Assessment and Leadership Transition
Thursday's gathering carries profound institutional significance as the final policy meeting chaired by Thomas Jordan, who is stepping down after leading the SNB through twelve turbulent years marked by negative interest rates, the 2015 franc shock, and the emergency rescue of Credit Suisse.
Jordan will hand the reins of the central bank on October 1 to current Vice Chairman Martin Schlegel. Analysts expect the incoming governor to maintain the SNB's hallmark pragmatism, balancing domestic price stability against the ever-present hazard of safe-haven currency overvaluation in a turbulent world economy.
Comments (0)
Log in to join the discussion.