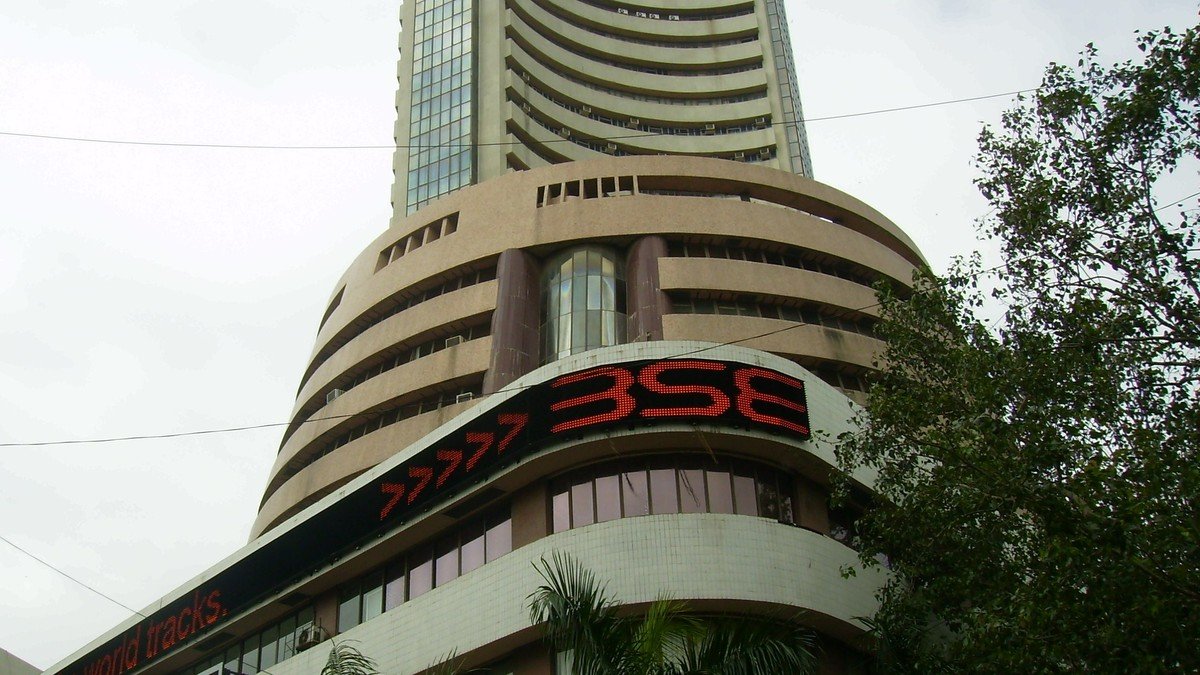
The Securities and Exchange Board of India (SEBI) has officially approved a comprehensive six-point regulatory overhaul for equity index derivatives, delivering on its commitment to protect retail investors from perilous speculative losses. Convening at its headquarters in Mumbai, the market regulator's board established stringent operational rules aimed at curbing an unprecedented explosion in retail trading across futures and options (F&O).
Under the new directives, the minimum contract value for index derivatives will be raised from ₹5 lakh to ₹15 lakh at the outset, with provisions to scale up to ₹20 lakh in subsequent phases. This threefold increase in contract size is explicitly designed to elevate entry barriers, ensuring that retail participants with limited capital are deterred from taking highly leveraged speculative bets.
Soaring Retail Speculation Triggers Comprehensive Regulatory Overhaul
In another decisive structural intervention, SEBI mandated that stock exchanges can each offer weekly expiry derivative contracts on only one single benchmark index. Currently, exchanges provide rolling daily expiries across multiple indices, creating hyper-speculative intraday churn that market studies revealed resulted in net trading losses for over 93 percent of individual retail participants.
The board also instituted mandatory upfront collection of option premiums from retail buyers by trading members. By disallowing brokers from extending intraday credit or margin relaxation for purchasing options, the regulatory framework ensures that traders can only execute positions backed by verified cash balances.
“Household savings flowing into speculative derivatives rather than productive capital formation poses macroeconomic risks. These measures restore prudent guardrails for retail participants.” — Madhabi Puri Buch, Chairperson of SEBI
Higher Capital Thresholds and Margin Safeguards Reshape Derivatives Landscape
Market data analyzed by SEBI revealed that Indian retail traders incurred aggregate net losses exceeding ₹1.8 lakh crore in equity derivatives over the preceding three fiscal years. Government and regulatory authorities voiced serious concerns that rampant financial gamification was diverting domestic household savings away from mutual funds and bank deposits into zero-sum financial speculation.
The phased implementation of these regulations is scheduled to commence on November 20, 2024, providing clearing corporations, exchanges, and discount brokerages a structured transition window. Market analysts anticipate a substantial compression in daily turnover volumes, which will foster deeper institutional stability across India's premier bourses.
Frequently Asked Questions
What is the new minimum contract value for index derivatives under SEBI's rules?
The minimum contract value has been increased from ₹5 lakh to ₹15 lakh, with the potential to rise to ₹20 lakh in future phases.
How will the new rules affect weekly expiry contracts on Indian exchanges?
Each stock exchange is restricted to offering weekly expiry derivative contracts on only one benchmark index instead of daily rotating expiries.
Comments (0)
Log in to join the discussion.