

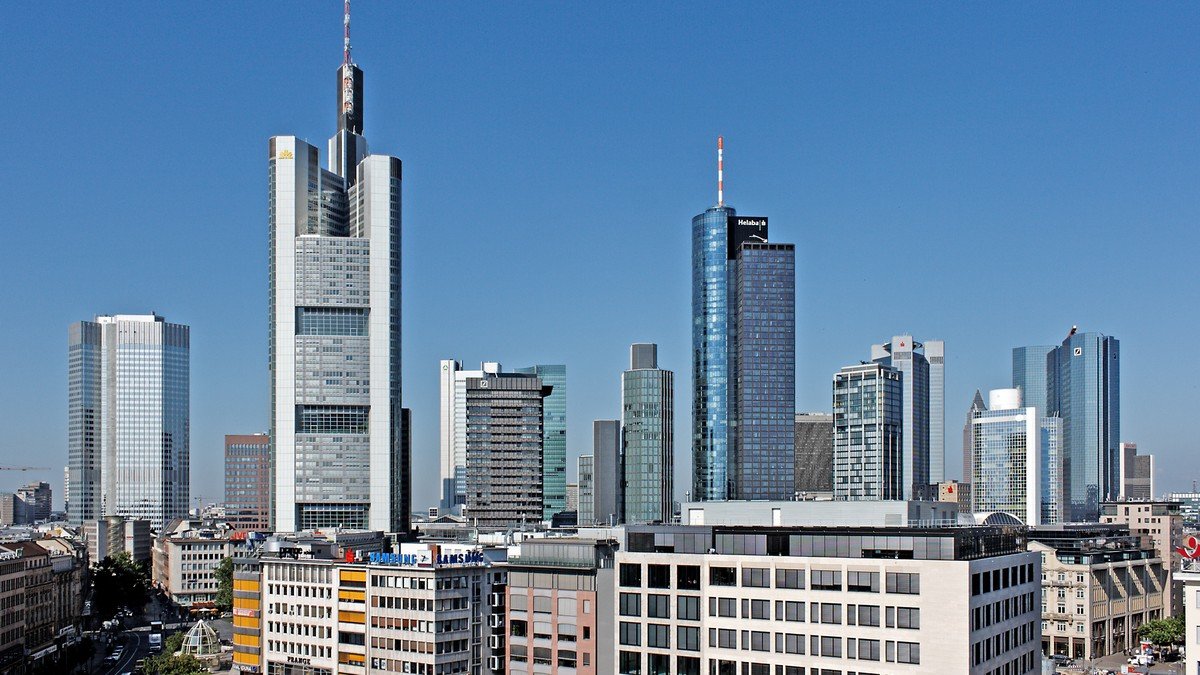
Europe's largest economy is poised to contract for the second year in a row, according to the joint autumn economic diagnostic report released Friday by Germany's five leading economic research institutes (Ifo in Munich, DIW Berlin, IfW Kiel, IWH Halle, and RWI Essen). The prominent think tanks slashed their 2024 gross domestic product (GDP) forecast to a contraction of 0.1%, reversing their earlier spring projection of a modest 0.1% expansion.
If realized, the downward revision confirms that Germany will suffer its first consecutive two-year recession in more than two decades, following a 0.3% GDP shrinkage recorded in 2023. The institutes also substantially trimmed their expectations for 2025, downgrading their projected growth trajectory from 1.4% to just 0.8%, signaling that any subsequent recovery will be exceptionally sluggish and fragile.
Second Consecutive Year of Contraction Confirmed by Think Tanks
The economists diagnosed Germany's predicament as a combination of cyclical stagnation and deep structural rot. Germany's energy-intensive industrial backbone—encompassing chemicals, automotive manufacturing, and heavy machinery—continues to reel from persistently elevated electricity and natural gas tariffs compared to international competitors in North America and Asia following the loss of cheap Russian pipeline gas.
In addition to unfavorable energy economics, German industrial exporters are facing severe headwinds from cooling demand in major export destinations, notably China, alongside fierce competition from subsidized foreign clean-technology manufacturers. Domestic business sentiment has deteriorated, with corporate leaders delaying capital expenditures due to crushing bureaucratic red tape and policy uncertainty within the Berlin governing coalition.
“The German economy is caught in stagnation. In addition to economic headwinds, structural shifts in industry, high energy expenses, and intense global competition are weighing heavily on growth.”
Structural Headwinds: High Energy, Deindustrialization, and Weak Investment
The joint forecast delivers a somber assessment to Federal Minister for Economic Affairs and Climate Action Robert Habeck, who will incorporate the findings into the federal government's updated autumn macroeconomic projections next month. The gloomy outlook intensifies pressure on Chancellor Olaf Scholz's coalition to implement structural tax relief, accelerate infrastructure permitting, and reform labor market incentives.
The prolonged slump in Germany is casting a widening shadow across the wider 20-nation euro area, where German manufacturing supply chains are deeply integrated with neighboring economies in Central and Eastern Europe. With industrial output remaining below pre-pandemic benchmarks, financial analysts expect the European Central Bank to intensify policy rate cuts to support faltering continental demand.
Comments (0)
Log in to join the discussion.